15 Mortgage Pre-Approval Mistakes First-Time Buyers Make (Before and After You're Approved)
By Emmett Clark, Mortgage Broker · NMLS #233747 · Updated
Most pre-approval problems come from 15 avoidable mistakes. Six happen before you apply. Nine happen after you're approved, between the letter and the closing table, and those are the ones that sink deals.
After more than 20 years in this business, I've watched the same mistakes trip people up again and again. Every one of them is avoidable.
Mistakes before you get pre-approved
1. Not checking your credit report before you apply
Errors like accounts that aren't yours, paid balances still showing, or old collections can cost you a better rate or program. Pull all three bureau reports early and dispute anything wrong, because fixes take time.
2. Confusing pre-qualification with pre-approval
A pre-qualification is an estimate based on what you tell a lender, while a pre-approval verifies your income and assets with documents, and sellers treat them very differently. Whether you're buying in California, Texas, Florida, or Colorado, know which one you're holding before you make a strong offer.
3. Letting your debt-to-income ratio creep up
Most lenders want your DTI at or below roughly 43%, and buyers forget debts underwriters count, like alimony, child support, deferred student loans, and co-signed accounts. Add it all up before you apply and pay down what you reasonably can, since one small payoff can move you into a better program.
4. Sending incomplete or inconsistent documents
Missing pay stubs, unsigned tax returns, and bank statements with pages left out are among the most common causes of delay. Send the full set up front: recent pay stubs, two years of W-2s or returns, and every page of every bank statement.
5. Shopping lenders the wrong way, or not at all
Rates and fees vary between lenders, and scoring models treat multiple mortgage inquiries within roughly 14 to 45 days as one inquiry. Compare offers in a focused window, and if you're weighing FHA against conventional, I broke that down in FHA vs. Conventional Loans in 2026.
6. Underestimating closing costs
Closing costs usually run 2% to 5% of the loan amount, on top of your down payment. Budget for the full cash to close from the start, and use our mortgage calculators to get in the right range.
Mistakes after you're pre-approved
7. Treating the pre-approval letter as a guarantee
The letter stays contingent on final verification of your income, assets, and debts, and on the home appraising. Keep your finances stable until you have the keys.
8. Opening new credit or financing a car or furniture
Your lender re-checks credit right up until funding, and a car loan, furniture financing, or new store card raises your DTI and can drop your score at the worst moment. Don't open, close, or take on any credit until you close, and call me first if you're not sure something counts.
9. Changing jobs, or going from salary to commission or self-employment, before closing
A new job, even a better one, can bring a probation period or an employment gap, and a switch to commission or self-employment can leave underwriting without the income history it needs to count your pay. Tell me before you make a move so we can time it around the loan.
10. Making large deposits you can't document
Underwriters have to source every large deposit to rule out borrowed money, and an unexplained one stalls the file. Gift funds are fine, including for the 3.5% minimum down on FHA loans or alongside down payment assistance, but they need a gift letter and a paper trail for large deposits.
11. Moving money between accounts without a record
Shifting funds between accounts, especially ones the lender hasn't seen, looks like a new deposit and has to be traced. Keep money where it is, and if you must move it, keep statements for both accounts showing it leave one and land in the other.
12. Co-signing for someone else
A loan you co-sign counts as your debt, even if someone else makes every payment. Hold off on co-signing anything until after you close.
13. Missing or paying late on any bill, including ones you think don't matter
One late payment, even on a small medical bill or utility that goes to collections, can drop your score before closing. Put everything on autopay until you have the keys.
14. Assuming your rate is locked
A pre-approval doesn't lock your rate, and until a lock is in place the rate you heard can move with the market. I lock once you have a signed contract and your documents are in, and you can check current rates anytime.
15. Letting your pre-approval expire
Pre-approvals are usually good for 60 to 90 days, because your credit and income need to be current. If your search runs long, stay in touch and we'll refresh it at no cost.
The Bottom Line
Nearly every pre-approval mistake traces back to the same root cause: not knowing what underwriters are actually looking at. Once you understand what can quietly derail a file, avoiding these traps is straightforward.
The simplest protection is communication. Tell me what's happening before you make a move, whether that's a job change, a large purchase, or a gift from family, and I can steer you around the problem instead of cleaning it up afterward.
Start With a Pre-Qualification
If you're a first-time buyer, a pre-qualification is exactly how I like to start. We'll get a clear, honest read on where you stand and map out the path to your first home.
Get Your Free Pre-Qualification or call me directly at (866) 617-7381 to talk it through.
Emmett Clark | NMLS #233747 | Serving borrowers in 18 states
Equal Housing Lender. Rates subject to change. Contact for personalized quote.
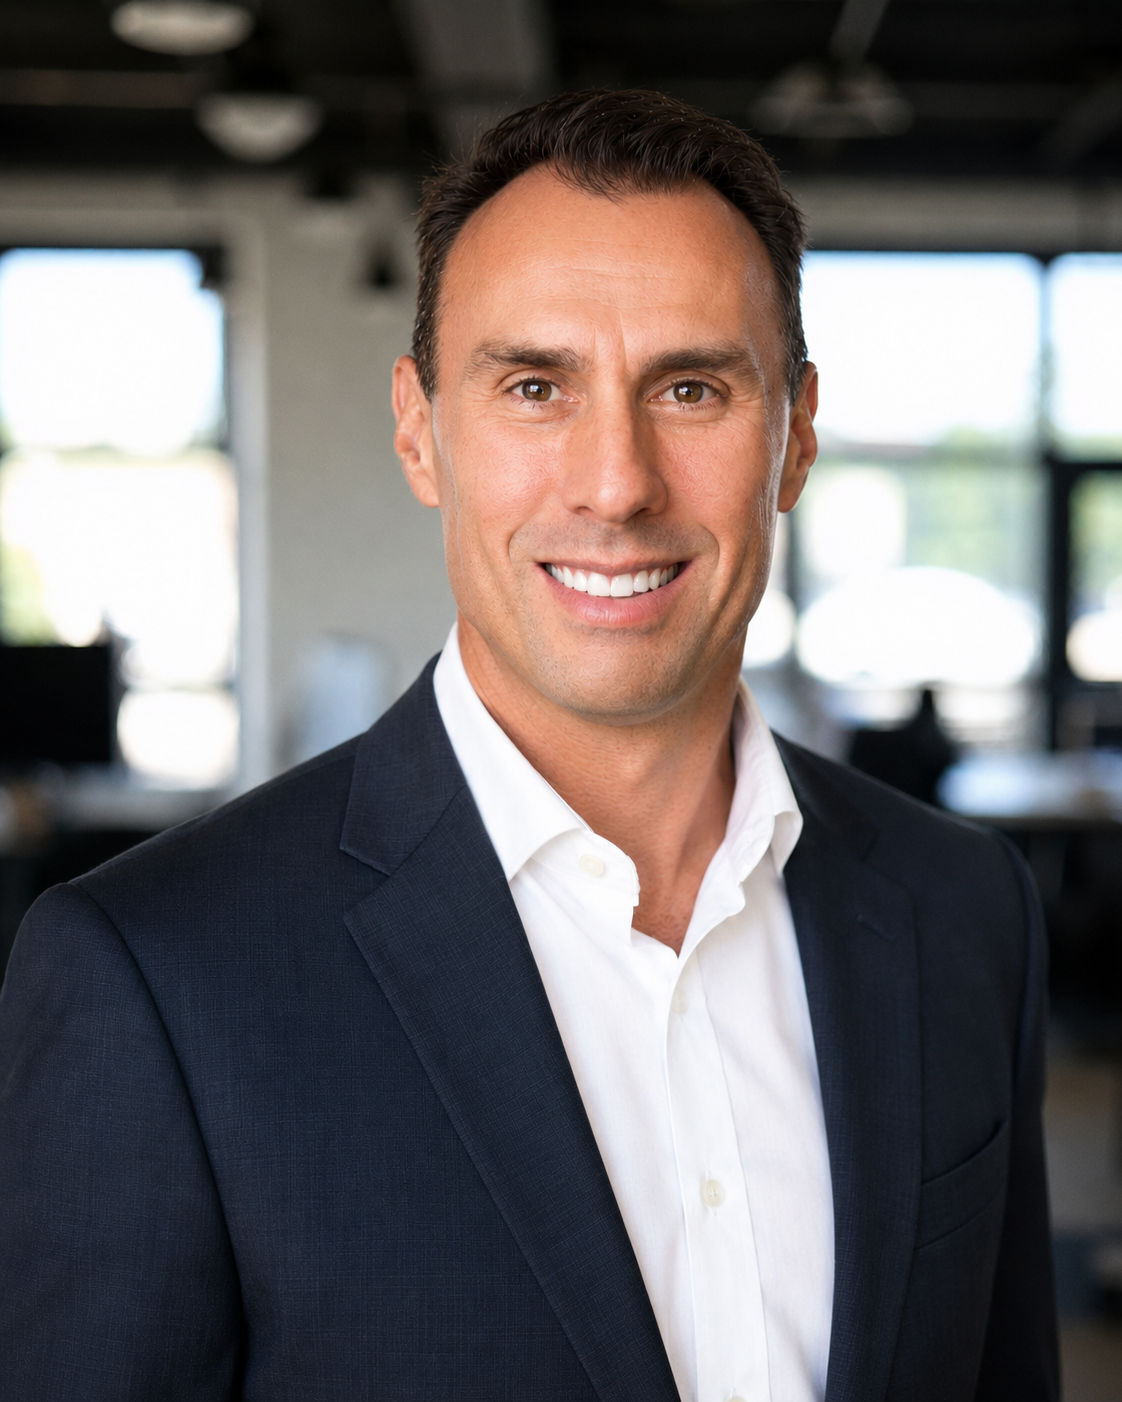
Emmett Clark
Licensed Mortgage Loan Officer · NMLS #233747 · 20+ Years Experience
This article has been reviewed for accuracy by Emmett Clark, a licensed mortgage professional serving homebuyers across 18 states including California, Texas, Florida, Arizona, and Colorado. Last updated: 2026-11-01.
About Emmett NMLS #233747
Emmett Clark (NMLS #233747) is a licensed mortgage professional with 20+ years of experience helping families achieve their homeownership dreams. Licensed in 18 states nationwide, Emmett specializes in finding the right mortgage solution for each client's unique situation. Powered by Loan Factory, Emmett provides access to competitive rates and a wide variety of loan programs including conventional, FHA, VA, and down payment assistance programs.
Work with Emmett