Florida Home Loans & Mortgage Programs
Florida offers homebuyers strong options across every loan type, plus advantages found in few other states: no state income tax, a Homestead Exemption that caps property-tax increases, and the Hometown Heroes program that provides up to $35,000 in down payment assistance for full-time Florida workers. Whether you are buying your first home in Tampa, a condo in Miami, a retirement home in Naples, or refinancing to cash out equity for a new roof, the right loan depends on your goals. As a broker licensed in Florida with access to 240+ wholesale lenders, I help buyers and homeowners across the Sunshine State find the best rate and the right program.
What are today's mortgage rates in Florida?
Here is a live look at today's conventional 30-year fixed pricing. Your actual rate depends on your credit, down payment, property type, and loan program.
Today’s 30-Year Fixed (Conventional) Rate
Conventional – Primary Residence
Rate Assumptions
30 year fixed, $300k loan amount, $400k value, purchase, FICO Credit Score 759, Zipcode 92867
APR & Disclosures
The Annual Percentage Rate (APR) shown reflects the cost of credit over the loan term, including applicable fees, and is based on the assumptions above. Your actual rate and APR depend on your credit profile, loan amount, property, occupancy, and other factors. For information purposes only and does not constitute a loan approval or commitment to lend. Rates are subject to change without notice.
Find Florida mortgage help in your region
Florida's markets vary widely, from South Florida's condo towers to the Panhandle's beaches to Central Florida's growing suburbs. Explore your region for local market context and loan guidance.
Southeast Florida (Miami, Fort Lauderdale, Palm Beach)
Condo-heavy, high-value coastal markets and jumbo territory.
Explore this regionMiami & South Florida
Luxury condos, international buyers, and jumbo financing.
Explore this region
Central Florida & Disney (Orlando)
Fast-growing suburbs and strong first-time-buyer demand.
Explore this regionOrlando Metro
Relocation hotspot with new construction and DPA-friendly prices.
Explore this region
West Central Florida (Tampa Bay)
Waterfront value, MacDill military community, and steady growth.
Explore this regionTampa Bay
One of Florida's most competitive and fastest-appreciating metros.
Explore this region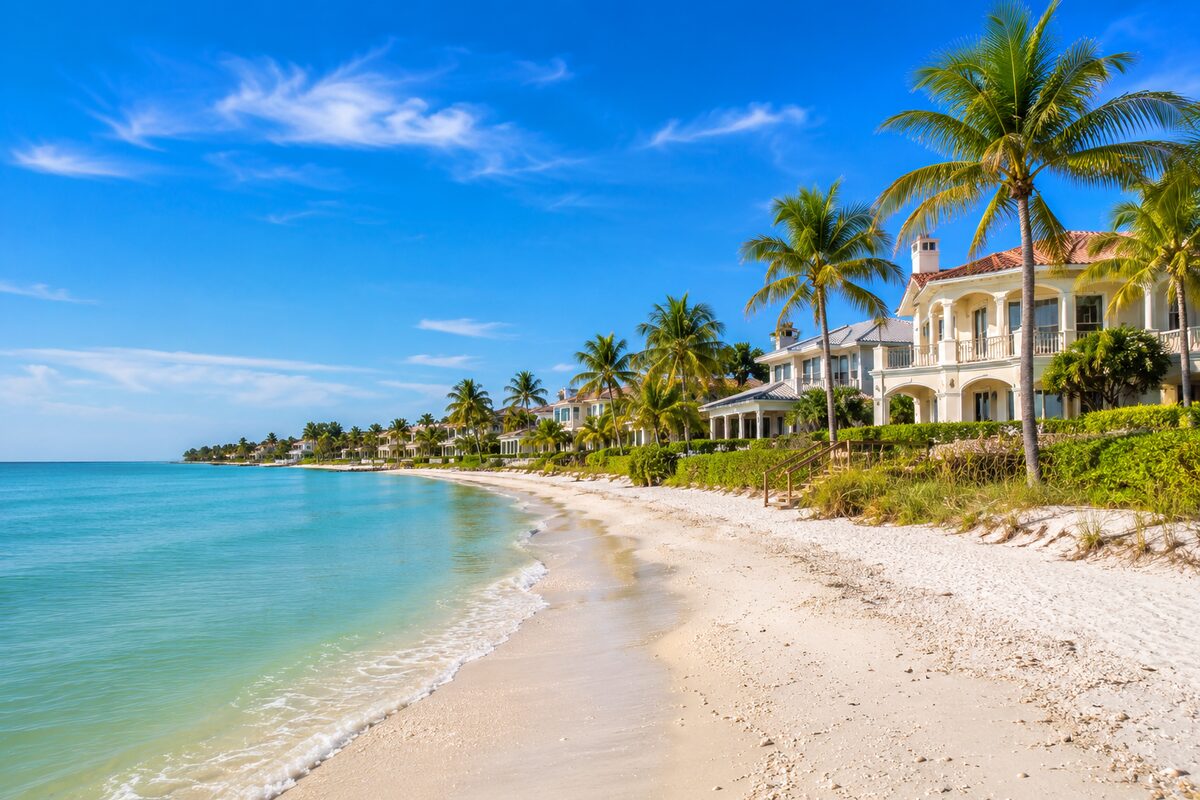
Southwest Florida (Naples, Fort Myers)
Upscale Gulf-coast markets, second homes, and jumbo demand.
Explore this region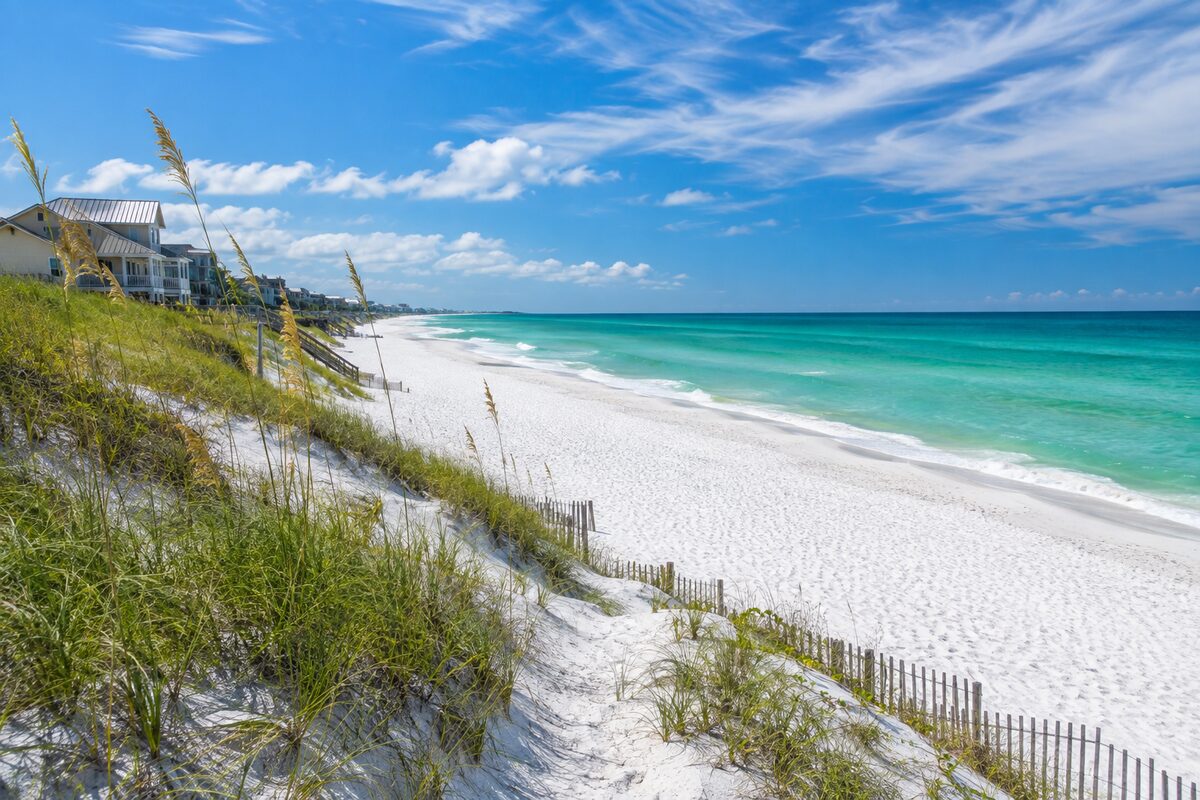
North Florida & Panhandle
Affordable beach towns and wide USDA eligibility.
Explore this region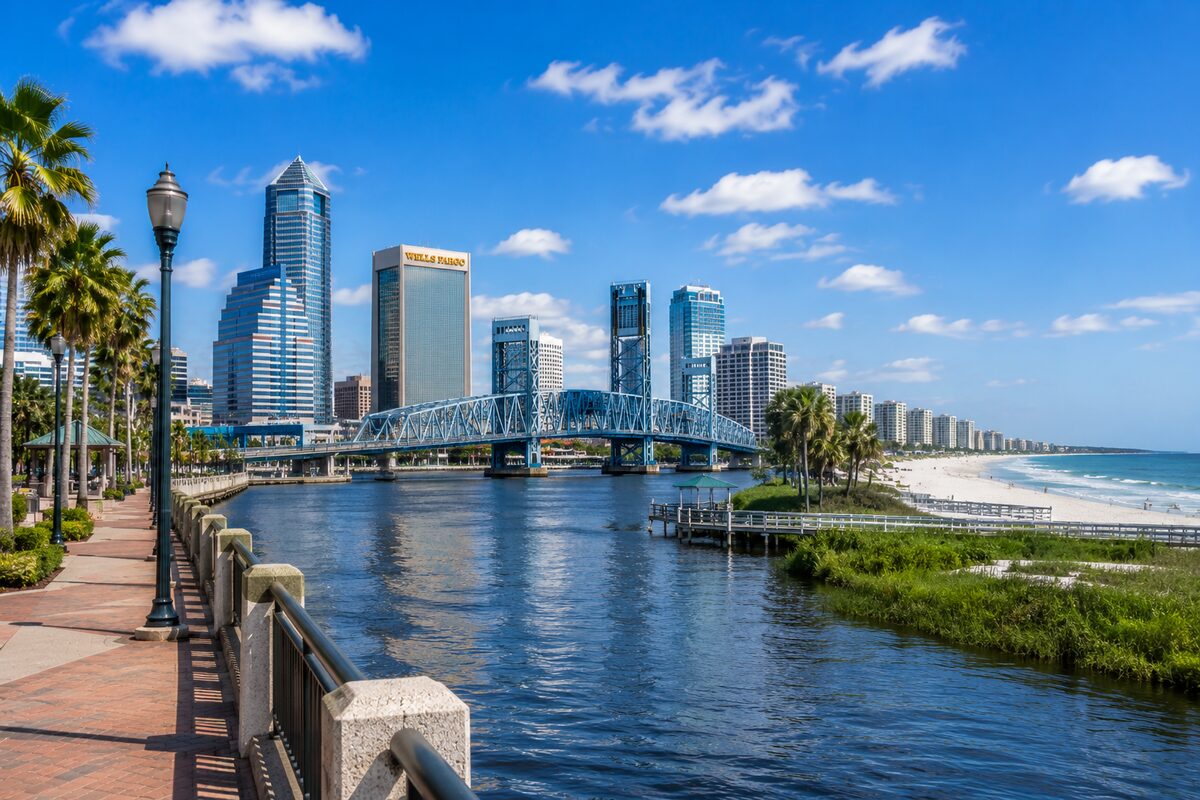
Northeast Florida & Jacksonville
NAS Jax military community, riverfront living, and value pricing.
Explore this regionWhat loan programs are available in Florida?
Florida buyers have access to every major loan type, and the best fit depends on your down payment, credit, and property. Conventional loans need as little as 3% down and let you cancel PMI at 20% equity. FHA loans work with 3.5% down and a 580 credit score. VA loans offer zero down for veterans and military, which matters in a state with 1.5 million veterans. USDA loans provide zero down in eligible rural and suburban areas, and far more of Florida qualifies than people expect. Jumbo loans finance luxury and coastal properties above the conforming limit. And for homeowners, refinancing can lower your rate or pull out equity, which in Florida is often used to fund a new roof that lowers insurance costs.
Conventional Loans
As little as 3% down, with PMI you can cancel at 20% equity.
Learn moreFHA Loans
3.5% down with a 580 credit score, flexible qualifying.
Learn moreVA Loans
Zero down for veterans and military in a state with 1.5M vets.
Learn moreUSDA Loans
Zero down in eligible suburban and rural areas statewide.
Learn moreJumbo Loans
Financing for luxury and coastal homes above the conforming limit.
Learn moreRefinance
Lower your rate or pull equity for a new roof to cut insurance costs.
Learn moreWhat down payment assistance is available in Florida?
Florida offers some of the strongest down payment assistance in the country, led by the Hometown Heroes program.
Hometown Heroes
Provides 5% of your first mortgage amount toward down payment and closing costs, with a minimum of $10,000 and a maximum of $35,000, as a zero-interest, non-amortizing second mortgage with no monthly payments. This assistance is not forgivable: the balance is repaid only when you sell, refinance, transfer title, or stop using the home as your primary residence. Open to full-time workers employed by a Florida-based, physical-location employer, requires a 640 credit score, and is for first-time buyers, though active-duty military and veterans are exempt from the first-time rule.
FL Assist
A $10,000 zero-interest second mortgage for down payment and closing costs, often paired with a Florida Housing first mortgage.
Florida Bond Program
Below-market 30-year fixed rates for eligible buyers. Many counties and cities layer additional local assistance on top of these state programs.
Not sure which program fits? A quick conversation tells you what you qualify for and how much assistance you can stack. Start your Florida pre-approval.
How does buying in Florida differ from other states?
Florida has no state income tax, which leaves more of your income available for a mortgage payment and is a major reason so many buyers relocate here from higher-tax states. The Homestead Exemption reduces the taxable value of a primary residence by up to $50,000 and caps annual assessment increases at 3 percent under the Save Our Homes benefit, keeping future tax bills predictable. Two Florida-specific costs deserve planning: homeowners insurance, which has risen sharply and now weighs heavily in qualifying, and flood insurance, which is required in many coastal and low-lying areas. A knowledgeable Florida broker factors realistic insurance and flood costs into your pre-approval so your budget reflects the true payment rather than a surprise at closing. Condos are their own world in Florida, with milestone-inspection and reserve requirements after the Surfside reforms, so condo financing takes specific expertise.
No State Income Tax
More monthly income available to qualify for your payment.
Homestead Exemption
Up to $50,000 off taxable value, 3% annual assessment cap.
Insurance & Flood
Real premiums built into your pre-approval, no surprises.
Condo Expertise
Post-Surfside milestone and reserve requirements handled.
Can I refinance my Florida home to pay for a new roof or lower my insurance?
Yes, and it is one of the smartest moves available to Florida homeowners right now. Florida's insurance crisis has made roof age a decisive factor in whether you can get affordable coverage at all, and many insurers will not write a policy on a roof beyond a certain age. A cash-out refinance lets you tap your home equity to fund a new roof, which can dramatically lower your insurance premium or make coverage obtainable in the first place, often producing a net monthly saving even after the refinance. Beyond roofs, a rate-and-term refinance can lower your payment when rates improve, and a cash-out refinance can consolidate higher-interest debt or fund improvements.
Lower Your Rate
Homeowners who locked in at 7%+ may qualify for meaningfully lower pricing today.
Cash-Out for a Roof
Fund a new roof or impact windows that lower your insurance premium.
Remove PMI
Appreciation may have pushed you past 20% equity, letting you drop PMI.
Consolidate Debt
Roll higher-interest balances into your mortgage to simplify payments.
Florida Refinance Calculator
Estimate your monthly savings instantly
Refinance Calculator
Compare your current mortgage with refinance options to see potential savings
Current Loan
New Loan
You'll recover your closing costs in 11 months (1 year)
The Roof & Insurance Cash-Out Strategy
Florida homeowners face some of the highest insurance premiums in the nation. A strategic cash-out refinance can fund upgrades that permanently reduce your annual insurance costs.
The Florida Insurance Crisis
- •Premiums have doubled or tripled for many homeowners since 2020
- •Older roofs (15+ years) are becoming uninsurable or costly to cover
- •Many carriers have left Florida, limiting options
- •Citizens Insurance has strict eligibility and rising rates
The Cash-Out Solution
- New Roof: Can reduce premiums 25-40% and make your home insurable with more carriers
- Impact Windows: Hurricane-rated windows can provide 15-25% wind mitigation discounts
- Roof-to-Wall Clips: Structural upgrades meeting Florida Building Code unlock discounts
- Opening Protection: Shutters and reinforced garage doors add protection credits
Example: The Math Behind This Strategy
Cash-Out for Roof + Windows
$35,000
Added to loan @ 6.5%
Monthly Payment Increase
~$220/mo
Amortized over 30 years
Annual Insurance Savings
$3,000-$5,000
= $250-$415/mo saved
Net Result: Many Florida homeowners come out ahead or break even on monthly costs while gaining a new roof, better hurricane protection, and long-term insurability.
2026 Florida Conforming Loan Limits
The 2026 baseline conforming limit is $832,750 for most Florida counties. Monroe County qualifies for a higher limit based on local home prices.
Standard Florida Counties
$832,750
Applies to most Florida counties including Miami-Dade, Orange, Hillsborough, Broward, Palm Beach, and Duval.
Monroe County (Florida Keys) High-Cost Limit
$1,249,125
Key West, Marathon, and Islamorada qualify for this elevated limit, the highest in Florida. Loans above these limits are jumbo loans.
Why choose Loans by Emmett for a Florida mortgage?
As a broker with access to 240+ wholesale lenders, I shop your loan across many lenders instead of offering the single rate sheet a bank is stuck with. That competition, paired with deep Florida-specific knowledge, is how my clients win.
240+ Lenders
Wholesale competition on every loan.
$2,000 Best Price Guarantee
Confidence you are getting a truly competitive deal.
Condo & Flood Expertise
Post-Surfside condos and flood-zone financing.
Florida Market Knowledge
Insurance-aware pre-approvals that hold up.
Florida Mortgage FAQs
What is the Florida Hometown Heroes program in 2026?
Florida Hometown Heroes provides 5% of your first mortgage amount in down payment and closing-cost assistance, with a minimum of $10,000 and a maximum of $35,000. It is a zero-interest, non-amortizing second mortgage with no monthly payments. It is not forgivable; the balance is due when you sell, refinance, transfer title, or stop using the home as your primary residence. You need a 640 credit score, full-time employment with a Florida-based employer, and first-time buyer status, though veterans and active-duty military are exempt from the first-time rule.
Does Florida have down payment assistance for first-time buyers?
Yes. The main programs are Hometown Heroes (up to $35,000, 5% of the loan), FL Assist (up to $10,000), and the Florida Bond program offering below-market 30-year fixed rates. Many counties and cities offer additional local assistance that can sometimes be combined.
Why is refinancing so common for Florida homeowners right now?
Florida's insurance crisis has made roof age critical to obtaining affordable coverage. Many homeowners use a cash-out refinance to fund a new roof, which lowers their insurance premium or makes coverage possible, often saving money overall. Refinancing is also used to lower a rate or consolidate debt.
What are Florida's 2026 conforming loan limits?
Most Florida counties use the 2026 baseline conforming limit of $832,750. Monroe County (the Florida Keys) uses the high-cost ceiling of $1,249,125 due to high property values. Loans above these limits are jumbo loans.
Do I need flood insurance to buy a home in Florida?
It depends on the property's flood zone. Many coastal and low-lying Florida properties require flood insurance, and lenders include it in your debt-to-income calculation. A good pre-approval estimates realistic flood and homeowners insurance for your target area so your budget is accurate.
Does most of Florida qualify for USDA zero-down loans?
More than people expect. While the major metro cores (Miami, Orlando, Tampa, Jacksonville) are excluded, many suburbs and rural areas 30 to 45 minutes out qualify, including much of Ocala/Marion, the Panhandle, and inland Central Florida.
Explore Florida Loan Programs
Dive into the details of any program below to see how it works in Florida.
Mortgage Broker
Why a Florida broker with 240+ lenders beats a single bank.
Pre-Approval
Start here with a real, insurance-aware pre-approval.
FHA Loans
3.5% down, 580 credit score, condo-friendly options.
VA Loans
Zero down for veterans and active-duty military.
Conventional Loans
3% down and cancellable PMI for stronger-credit buyers.
USDA Loans
Zero down in eligible rural and suburban Florida.
Jumbo Loans
Luxury and coastal financing above conforming limits.
Ready to start your Florida home loan?
Whether you are buying your first home, moving to the Sunshine State, or refinancing to cut your insurance costs, let's find the right program and the best rate.
From the blog & learning center
Florida Home Buying Guides
Condo Loan Denied Over the HOA? FHA Single Unit Approval May Save the Deal
If your condo loan was denied because of the HOA project itself, not your credit, FHA Single Unit Approval may still get you to closing. Here is how it works.
Read more
How to Buy a House After Divorce
Buying after divorce means untangling the old mortgage, documenting support income, and qualifying on your own. Here is how to prepare and what lenders look at.
Read more
FHA-Approved Condos in Hawaii: Why the List Is Short, and How to Find One
Only a small number of Hawaii condos are FHA-approved, so you must confirm a unit qualifies before you fall in love with it. Here is how FHA condo approval works in Hawaii.
Read more
Can You Buy a 5 to 8 Unit Property With an FHA Loan?
No. FHA financing caps at 4 units. A 5-unit-or-larger building is commercial and needs different financing. Here is why, and what to use instead.
Read more
Buying a House After Bankruptcy: Real Waiting Periods by Loan Type
FHA and VA require 2 years after Chapter 7, USDA 3, conventional 4. Chapter 13 can qualify after 12 months of payments, and one program works during bankruptcy.
Read more
Buying After Foreclosure or Short Sale: The Real Timelines
After foreclosure, VA requires 2 years, FHA and USDA 3, conventional 7. Short sales are shorter, and some paths skip the waiting period entirely.
Read more