Tennessee USDA Loans 2026
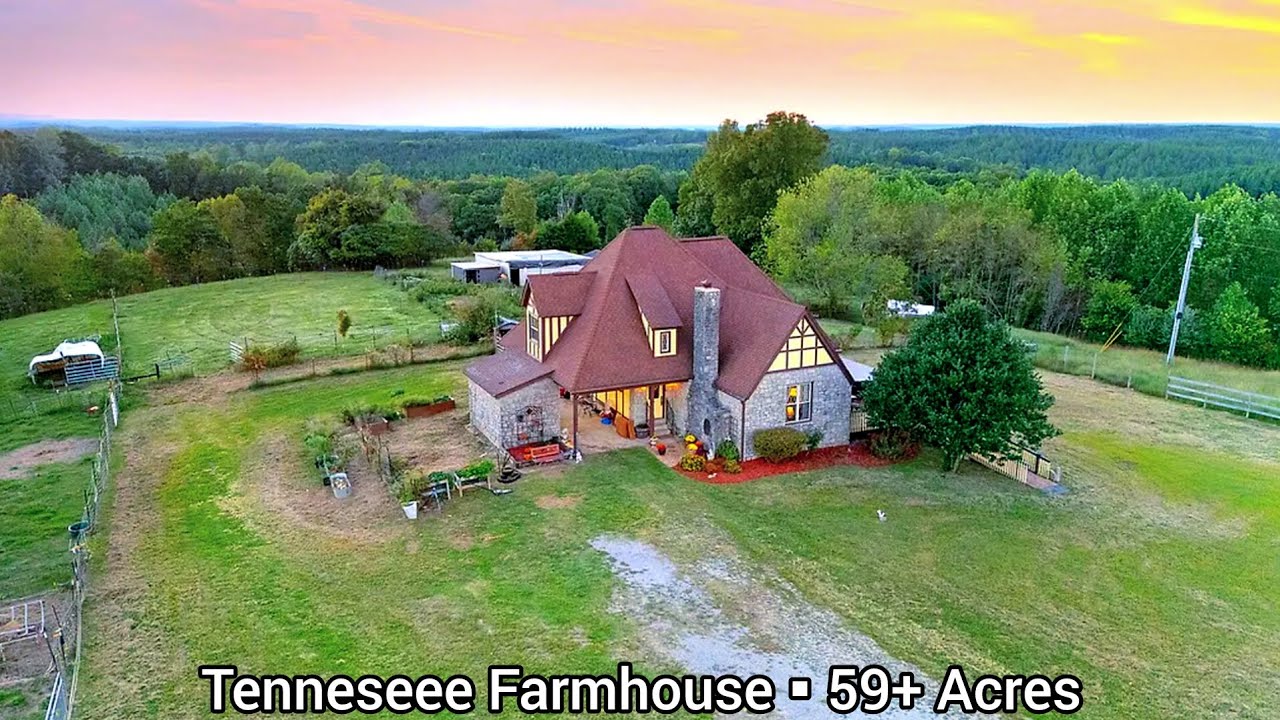
Yes, eligible Tennessee buyers can purchase a home with zero down through a USDA loan, and roughly 97% of Tennessee's land area qualifies. Eligibility depends on the property's location and your household income, so many communities within commuting distance of Nashville, Knoxville, and Chattanooga are eligible.
Tennessee's rural character means thousands of properties qualify for USDA Rural Development financing with zero down payment. From growing communities like Lebanon to scenic areas around Soddy-Daisy and the rural corners of Spring Hill, USDA loans make homeownership achievable for moderate-income families seeking space, nature, and affordable living. See how USDA rural home loans work nationwide.
How do USDA loans work in Tennessee?
The USDA Rural Development Guaranteed Housing Loan Program helps moderate-income buyers purchase homes in eligible rural areas with exceptional terms. It is worth comparing against the full range of Tennessee mortgage options before committing.
More Tennessee Qualifies Than You Think
Many Tennessee buyers assume USDA loans only work for remote farmland, but the program's definition of "rural" is surprisingly generous. According to how USDA defines an eligible property, approximately 97% of Tennessee's land area and 35% of its population live in USDA-eligible zones. This includes thriving communities within commuting distance of Nashville, Knoxville, Chattanooga, and Memphis.
The Department of Agriculture periodically updates eligibility boundaries, and areas can lose eligibility as they urbanize. Some Tennessee communities currently on the border of eligibility may not qualify in future years, creating urgency for buyers considering these locations. Checking current eligibility early in your home search prevents disappointment later, and a Tennessee mortgage broker who tracks USDA boundary changes can confirm your status before you make an offer.
Income limits for USDA loans are based on 115% of area median income, adjusted for household size. In many Tennessee counties, a family of four can earn over $100,000 annually and still qualify, making USDA accessible to a broad range of moderate-income households.
What areas in Tennessee are USDA eligible?
These areas currently have significant USDA-eligible zones
| Region | Eligible Areas | Market Status |
|---|---|---|
Middle Tennessee | Lebanon, Mt. Juliet outskirts, Spring Hill edges, Columbia (Maury County), Cookeville (Putnam County), Dickson County, Robertson County, Smith County | Highly Active |
East Tennessee | Jefferson County, Sevier County outskirts, Blount County rural, Anderson County, Campbell County, Grainger County | Strong Demand |
Southeast Tennessee | Cleveland (Bradley County), McMinn County, Rhea County, Meigs County, Polk County, Hamilton County outskirts | Growing Market |
Cumberland Plateau | Crossville (Cumberland County), Cookeville outskirts, Putnam County rural, Fentress County, Van Buren County | Fully Eligible |
West Tennessee | Fayette County, Tipton County, Haywood County, Madison County, Gibson County, Henry County | Affordable Options |
Important: USDA eligibility is determined by specific property address, not just city or county. Always verify eligibility using the official USDA eligibility map before making offers. Boundaries can change annually.
USDA Opportunities by Tennessee Region
Each region offers unique rural lifestyle options
Middle Tennessee USDA Markets
The Nashville metro's rapid expansion has reduced USDA eligibility in core areas, but outlying communities still qualify. Lebanon's rural sections, parts of Wilson County, and the Dickson County corridor offer USDA-eligible properties within 30-45 minutes of Nashville employment. Spring Hill's outer areas may still qualify, though eligibility is declining as the area urbanizes.
Check Your USDA Eligibility in 60 Seconds
Enter your zip code, household size, and income to see if you likely qualify for 100% financing with zero down payment.
USDA Eligibility Quick Check
See if you qualify for 100% financing in under 60 seconds
Count everyone who will live in the home
Combined income of all adults in the household
Optional: Income Adjustments (may lower your adjusted income)
Deductions: $480/child, $400/senior or disabled member
This is a preliminary screening tool using current baseline income limits. Actual eligibility depends on your specific property address and county limits. Call (866) 617-7381 for definitive answers.
Pro Tips for Tennessee USDA Buyers
- 30 minutes = eligibility. Areas just outside Nashville, Memphis, and Knoxville often qualify for USDA financing.
- Income deductions help. Childcare costs, dependents, and disabilities can lower your “adjusted” income below the limit.
- Some counties have higher limits. Williamson and other high-cost counties allow more income than the standard threshold.
- Eligibility can change. USDA periodically updates area boundaries. Communities on the metro fringe may lose eligibility as they urbanize, so checking early matters.
Popular USDA-Eligible Tennessee Markets
Cookeville
Putnam County, fully eligible
Columbia
Maury County, booming growth
Crossville
Cumberland Plateau, 100% eligible
Cleveland
Bradley County, mountain views
What are the USDA income limits in Tennessee?
1-4 Person Household
The 2026 standard income limit for most Tennessee counties is:
This is the standard limit for most areas; some high-cost metros are higher, so we confirm the property’s county at pre-approval.
5-8 Person Household
Larger households receive higher income limits to accommodate more earners:
This is the standard limit for most areas; some high-cost metros are higher, so we confirm the property’s county at pre-approval.
Note: Income limits include ALL household income, not just borrowers on the loan. This includes adult children living at home, elderly parents, and anyone contributing to household expenses.
“We never imagined buying a home with zero down payment was possible. We thought those programs were myths. Emmett checked USDA eligibility for several properties we liked in Wilson County and found our dream home on 2 acres that qualified. The 0.35% annual fee is a fraction of what PMI would cost, and we put the money we would have saved for a down payment into furnishing our new home. Living outside Lebanon gives us space for our kids and dogs while I still commute to Nashville in 35 minutes.”
What are the USDA requirements in Tennessee?
Location Requirements
- Property in USDA-eligible rural area
- Population typically under 35,000
- Must be primary residence
- No income-producing farms
Income Requirements
- Below 115% of area median income
- All household income counted
- Stable employment history
- Debt-to-income up to 41%
Property Requirements
- Must be modest for the area
- Meet USDA property standards
- Land value <30% of total value
- No swimming pools (typically)
Expert Insight
“USDA is Tennessee's most underutilized loan program. I regularly work with buyers who assumed they didn't qualify, only to discover their preferred neighborhood is USDA-eligible. The program's income limits are more generous than most expect, and families earning over $100,000 often qualify. My advice: always check eligibility before assuming you need a down payment. Zero down with a 0.35% annual fee beats FHA's costs significantly for those who qualify.”
Tennessee USDA Loan Questions
What areas in Tennessee are USDA eligible?
Large portions of Tennessee qualify for USDA financing, including areas outside major metro cores. Eligible regions include much of Wilson County (Lebanon area), Maury County suburbs, East Tennessee communities, and West Tennessee rural areas. Surprisingly, some suburbs within 30 minutes of Nashville, Knoxville, and Chattanooga still qualify.
What are Tennessee USDA income limits for 2026?
Tennessee USDA income limits for 2026 are $122,800 for a 1-4 person household and $162,100 for a 5-8 person household in most counties. Some high-cost metros have higher limits. These limits apply to total household income, not just the borrower.
What credit score do I need for a USDA loan in Tennessee?
Tennessee USDA loans typically require a minimum 640 credit score for automated underwriting approval. Borrowers with scores between 580-639 may still qualify through manual underwriting with compensating factors like stable employment, low debt ratios, or significant savings.
How much is USDA guarantee fee in Tennessee?
Tennessee USDA loans have a 1% upfront guarantee fee (can be financed) plus an annual fee of 0.35% of the loan balance. For a $300,000 loan, this equals $87.50 per month in annual fee, significantly less than FHA mortgage insurance at approximately $137.50 per month.
Can I buy a home with land using Tennessee USDA financing?
Yes, Tennessee USDA loans can finance homes with acreage as long as the property does not generate income. The land value should not exceed 30% of total appraised value. This makes USDA ideal for Tennessee buyers seeking rural homesites with space for gardens, animals, or recreation.
Tennessee USDA Loans by Area
Ready to Explore Tennessee USDA Financing?
Get pre-approved for a Tennessee USDA loan in minutes and discover zero-down rural homeownership.
Explore Other Tennessee Loan Options
From the blog & learning center
USDA Loan Guides & Articles
Gift Funds: The Rules for Down Payment Gifts
A family member can give you money for your down payment, and on most loan types the entire down payment can be a gift. The key rules: it has to be a true gift with no repayment expected, it must come from an acceptable source, and it has to be documented with a gift letter and a clear paper trail.
Read moreSeller Concessions: How Much Can the Seller Pay?
A seller concession is when the seller agrees to pay part of your closing costs as a term of the sale. It's a legitimate, common way to reduce your cash to close, and depending on the loan type and your down payment, a seller can contribute anywhere from 2% to 9% of the purchase price toward your costs.
Read moreWhat Credit Score Do You Need for Each Loan Type?
The minimum credit score depends entirely on the loan program: FHA goes as low as 500-580, VA and USDA have no federal minimum (lenders typically want 580-640), conventional generally starts around 620, and jumbo loans want 700 or higher. Here's the breakdown by program.
Read more
How Can You Buy a House With No Money Down?
Two true zero-down loans exist: VA for veterans and military, and USDA for eligible rural and suburban homes. A few other paths get you close.
Read more
USDA Loan Income Limits 2026: How Much You Can Earn and Still Qualify
The 2026 USDA income limit is $112,450 for a 1-4 person household in most of the country, and $148,450 for a 5-8 person household, higher than most people assume.
Read more
Is My Address USDA Eligible? How the Rural Map Actually Works
Roughly 97% of U.S. land area is USDA-eligible, including far more suburbs than people expect. Eligibility comes down to your exact street address, not your zip code.
Read more