Learn → Refinancing
Refinancing
Refinancing can lower your rate, shorten your term, or turn equity into cash — but only when the math genuinely works in your favor. This hub explains when a refinance makes sense, how closing costs factor in, and the traps to avoid so you do not reset your clock for the wrong reasons.
All Refinancing articles & guides
When Does Refinancing Make Sense? How to Calculate Your Break-Even
Refinancing makes sense when monthly savings recover your closing costs before you sell. Divide costs by savings to find your break-even in months.
Read more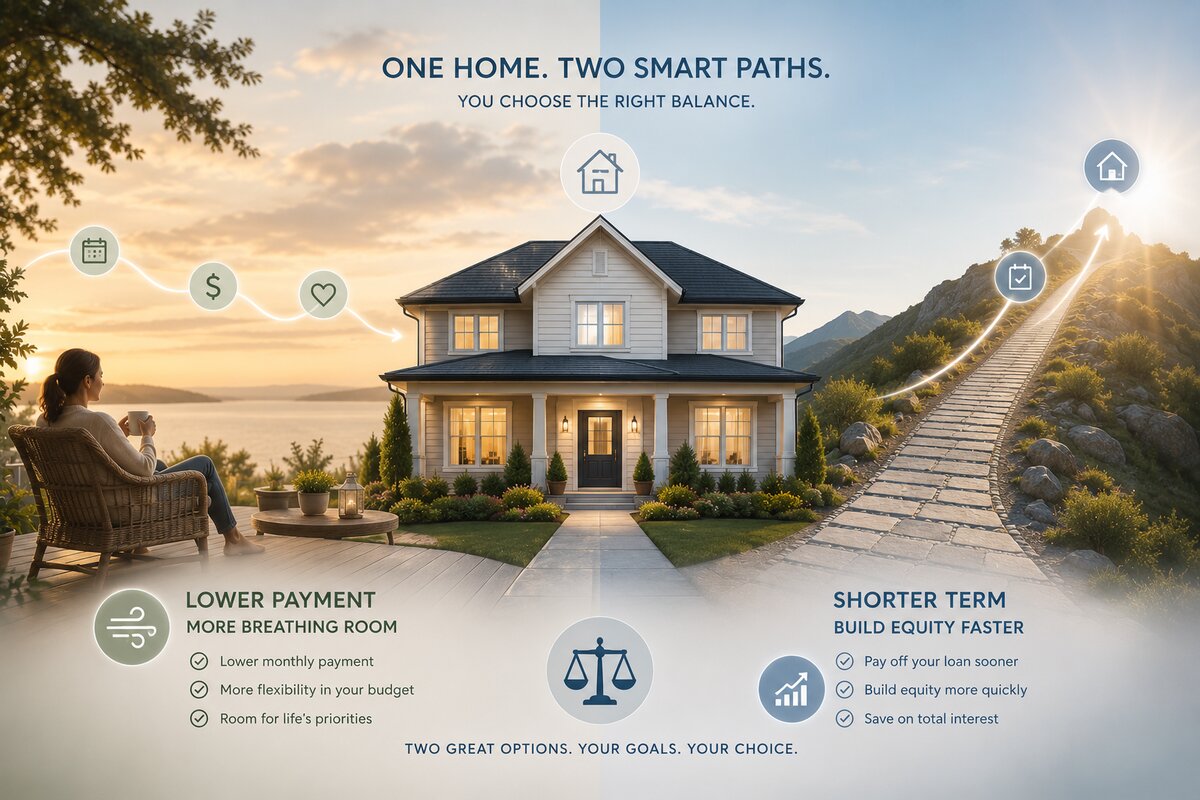
Refinance to Lower Your Payment or Pay Off Faster? A Net-Benefit Breakdown
Lowering your payment frees cash flow but costs more interest; paying off faster saves interest but tightens your budget. Here's how to choose.
Read more
VA IRRRL and FHA Streamline: Refinancing Without the Full Process
A streamline refinance lowers your rate on an existing FHA or VA loan with no appraisal or income docs in most cases. Learn the IRRRL and FHA Streamline rules.
Read more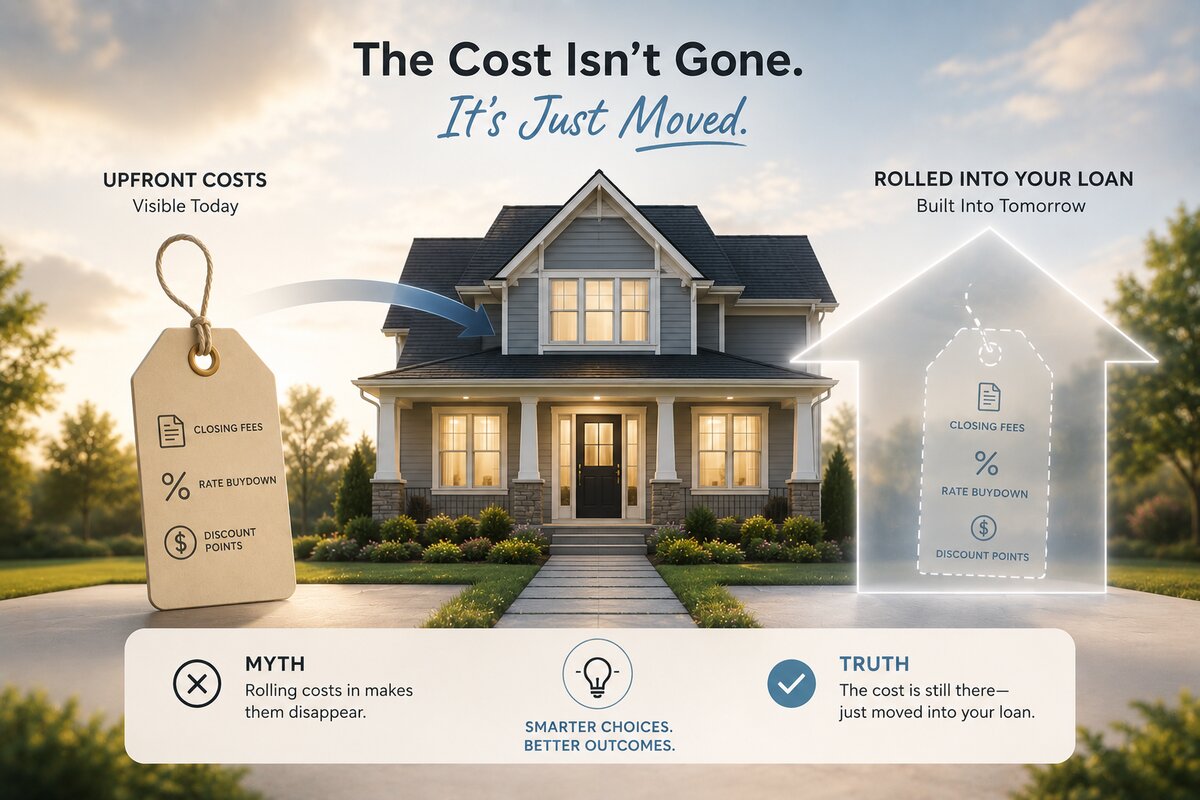
No-Closing-Cost Refinance: Is It Really Free?
A no-closing-cost refinance isn't free. The costs are paid through a higher rate or added to your balance. Learn when the trade is worth it.
Read more
Cash-Out Refinance Explained
A cash-out refinance replaces your mortgage with a larger loan, up to 80% of your home's value, and pays you the difference. Learn how much you can get.
Read more
Types of Refinancing Explained: Rate-and-Term, Cash-Out, and Streamline
There are three main types of mortgage refinancing: rate-and-term, cash-out, and streamline. Each solves a different problem, and picking the wrong one is the most common refinancing mistake.
Read moreThinking about refinancing?
Check current refinance rates and see how much you could save.
Prefer to talk? Call (866) 617-7381