California Home Loans & Mortgage Programs
California offers homebuyers every major loan program across wildly different markets, from Bay Area tech hubs to Southern California's coast to the Central Valley's more affordable communities. Whether you are a first-time buyer using the Price Equalizer to get elite pricing with a small down payment, a veteran near Camp Pendleton, a tech professional in San Jose, or a family in Sacramento, the right loan depends on your goals and your region. As a broker licensed in California (CA-DRE #01408122) with access to 240+ wholesale lenders, and based right here in San Jose, I help buyers across the Golden State find the best rate and the right program.
What are today's mortgage rates in California?
Today’s 30-Year Fixed (Conventional) Rate
Conventional – Primary Residence
Rate Assumptions
30 year fixed, $300k loan amount, $400k value, purchase, FICO Credit Score 759, Zipcode 92867
APR & Disclosures
The Annual Percentage Rate (APR) shown reflects the cost of credit over the loan term, including applicable fees, and is based on the assumptions above. Your actual rate and APR depend on your credit profile, loan amount, property, occupancy, and other factors. For information purposes only and does not constitute a loan approval or commitment to lend. Rates are subject to change without notice.
The California Price Equalizer: Same Rate as 40% Down
California's high-cost markets carry the steepest Loan-Level Pricing Adjustments in the country, the fees that normally penalize a smaller down payment. But there is a Fannie Mae rule that waives them entirely for first-time buyers under the area income limit, which in California's high-cost metros rises to 120% of Area Median Income. That means a qualifying first-time buyer with 3, 5, or 10% down can be priced the same as someone putting 40% down. We call it the Price Equalizer. In San Jose, the nation's highest limit, a household earning up to $177,643 can qualify, and many tech professionals qualify on base salary alone even when total compensation is much higher.
AMI figures are pulled from the current Fannie Mae area limits. Because AMI is address-specific, always confirm your exact limit for your address.
Estimate your Price Equalizer savings
Run your numbers below. By waiving the LLPA fees, which typically cost 1% to 2% of the loan amount, your monthly payment and cash to close drop significantly.
California Price Equalizer Tool
See if you qualify for LLPA fee waivers
Find California mortgage help in your region
From the Golden Gate to the Sierra Nevada, California is really many housing markets in one state. Explore the region and city closest to you.
Golden Gate Bridge
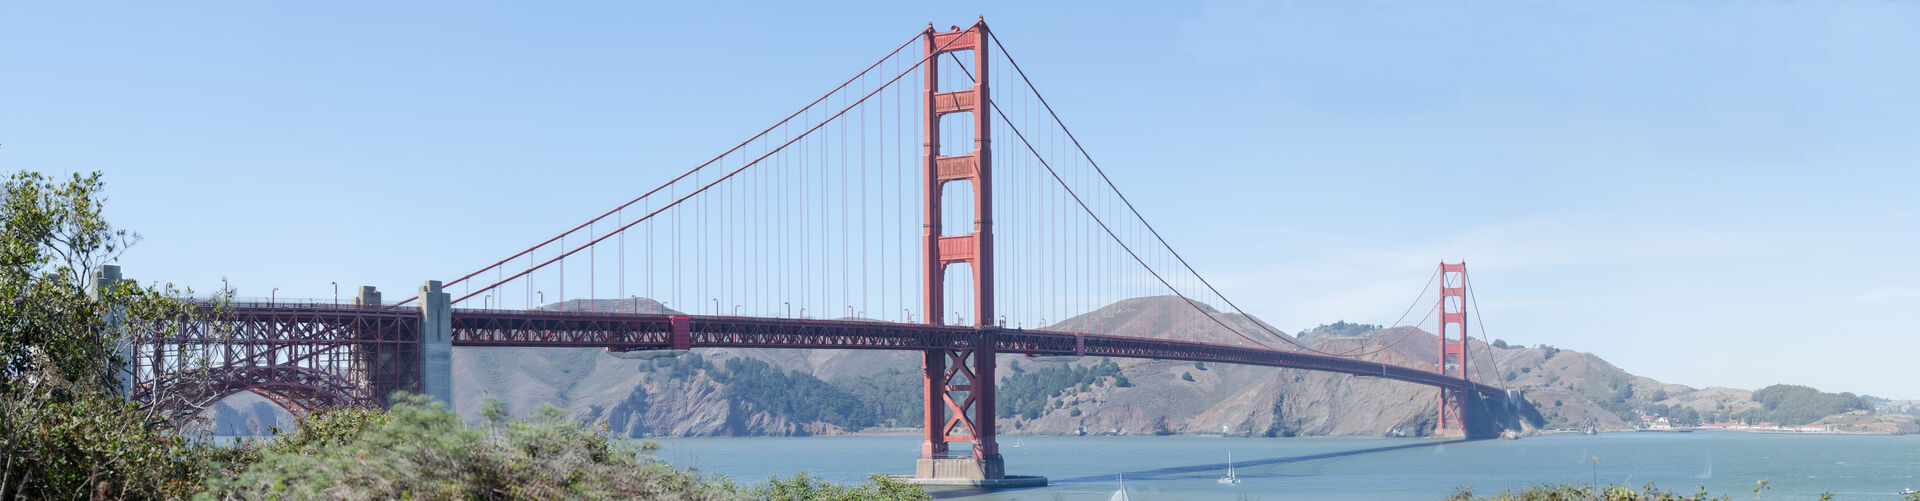
The iconic Golden Gate Bridge stands as a symbol of San Francisco's innovation and beauty. This world-renowned landmark defines the Bay Area's skyline and represents the region's engineering excellence.
Mortgage Market Insight
San Francisco Metro AMI Limit: $201,720
Median Home Price: $1.4M
Popular Loans: Jumbo, Conventional, FHA
Price Equalizer Savings: $10,000-$15,000+
Regional Advantage: Bay Area tech professionals can waive LLPA fees by qualifying on base salary alone
← Swipe to explore California landmarks →
Bay Area
SoCal Coastal
SoCal Inland
Central Valley
What loan programs are available in California?
California buyers have access to every major loan type, and the best fit depends on your down payment, credit, region, and property. Conventional loans need as little as 3% down and let you cancel PMI at 20% equity, with high-balance conforming limits up to $1,249,125 in the highest-cost counties. FHA loans work with 3.5% down and a 580 credit score, with FHA limits also reaching $1,249,125 in high-cost areas. VA loans offer zero down for California's 1.8 million veterans, plus CalVet benefits. Jumbo loans finance the luxury and coastal markets above the conforming limit. And first-time buyers under the area income limit can use the Price Equalizer for elite pricing regardless of down payment.
What down payment assistance is available in California?
California offers strong assistance through CalHFA, the state housing agency. The CalHFA MyHome Assistance Program provides a deferred junior loan of up to 3.5% of the purchase price to cover your down payment, and the CalHFA Zero Interest Program (ZIP) offers additional closing-cost help at 0% interest. These pair with FHA, VA, USDA, and conventional loans and are aimed at first-time buyers within county income limits. We also offer our own FHA down payment grant, which unlike CalHFA's deferred loans requires no repayment. And for first-time buyers, the Price Equalizer can deliver savings that rival a down payment assistance program by eliminating LLPA fees entirely.
How does buying in California differ by region?
California is really many housing markets in one state. The Bay Area and coastal Southern California are among the most expensive in the nation, where jumbo financing, the Price Equalizer, and careful structuring around the conforming limits matter most. The Central Valley, from Sacramento to Fresno to Bakersfield, is dramatically more affordable and is strong FHA and first-time-buyer territory. The Inland Empire (Riverside, San Bernardino) offers relative value within reach of the coast. And military communities like San Diego and near Camp Pendleton are among the best VA markets in the country. Because pricing, limits, and strategy shift so much by region, I tailor the loan to your specific California market.
Why choose Loans by Emmett for a California mortgage?
I am based right here in San Jose (CA-DRE #01408122, NMLS #233747), with more than 20 years in California lending and access to 240+ wholesale lenders. That means I can shop your loan instead of fitting you into one bank's box, whether you need Price Equalizer expertise, tech-income and RSU structuring, a deep jumbo network, or CalHFA and grant knowledge. Start with a California mortgage broker who knows your region, or get a real pre-approval before you shop.
California Mortgage FAQs
What is the California Price Equalizer?
What are California's 2026 loan limits?
Does California have down payment assistance?
What is the best loan for a California veteran?
Do I need a jumbo loan in California?
Explore California Loan Programs
Detailed guides for every loan program available in California, including 2026 loan limits, eligibility, and down payment options.
Why a California broker with 240+ lenders beats a single bank.
View detailsStart here with a real, region-aware pre-approval.
View details3.5% down, 580 credit score, limits up to $1,249,125.
View detailsZero down for California veterans, plus CalVet benefits.
View details3% down and cancellable PMI for stronger-credit buyers.
View detailsZero down in eligible rural and inland California.
View detailsLuxury and coastal financing above conforming limits.
View detailsReady to find your California loan?
Let's review your goals, your region, and your income structure to match you with the best rate and program. Most consultations take just 15 minutes.
From the blog & learning center
California Home Buying Guides
How to Afford a Million Dollar House
To comfortably afford a $1 million home you generally need household income between roughly $155,000 and $220,000, a down payment of $100,000 to $200,000, and enough reserves for closing costs and a few months of payments.
Read more
How to Buy a House With Bad Credit
You can buy a house with bad credit, it just takes the right loan program and some strategy. FHA loans accept scores as low as 500, and there are concrete steps to strengthen your application even when your credit isn't where you'd like it.
Read more
How Can You Buy a House With No Money Down?
Two true zero-down loans exist: VA for veterans and military, and USDA for eligible rural and suburban homes. A few other paths get you close.
Read more
What Is a Jumbo Loan? (2026 Limits)
A jumbo loan is a mortgage that exceeds the 2026 conforming limit of $832,750 in most counties, or $1,249,125 in high-cost areas.
Read more
Jumbo Loan Requirements in 2026
To qualify for a jumbo loan in 2026, most lenders look for a 700+ credit score, 10-20% down, DTI at or below 43%, and cash reserves after closing.
Read more
Jumbo Loan Down Payment: How Much You Really Need
You don't necessarily need 20% down for a jumbo loan. In 2026, well-qualified borrowers can find financing with as little as 10% down on loans up to roughly $2 million.
Read more