California VA Loans: Zero Down for Golden State Veterans
California's 1.8 million veterans deserve the best home financing available. VA loans offer$0 down payment, no PMI, and thelowest rates on the market, with no loan limits for those with full entitlement.
Yes, eligible California veterans, active-duty service members, and surviving spouses can buy a home with zero down payment and no monthly mortgage insurance, with no loan limit at all for those with full entitlement, which matters enormously in California's expensive markets. California is home to roughly 1.8 million veterans and more military installations than any other state, from Camp Pendleton to Naval Base San Diego to Travis Air Force Base. On top of the federal VA benefit, California offers the CalVet Home Loan Program and generous disabled-veteran property tax exemptions. As a broker licensed in California (CA-DRE #01408122) with access to 240+ wholesale lenders, I help veterans use the full stack of benefits they have earned.
What are today's VA loan rates in California?
Today’s 30-Year Fixed VA Rate
VA – Primary Residence
Rate Assumptions
30 year fixed, $300k loan amount, $400k value, purchase, FICO Credit Score 759, Zipcode 92867
APR & Disclosures
The Annual Percentage Rate (APR) shown reflects the cost of credit over the loan term, including applicable fees, and is based on the assumptions above. Your actual rate and APR depend on your credit profile, loan amount, property, occupancy, and other factors. For information purposes only and does not constitute a loan approval or commitment to lend. Rates are subject to change without notice.
Why do California veterans choose VA loans?
In a state where saving 20% for a down payment can take a decade, the VA loan's zero-down structure is transformative. On a $900,000 San Diego home, a conventional 20% down payment is $180,000, while the VA down payment is zero. VA loans also never require private mortgage insurance regardless of down payment, which on a $700,000 California loan saves roughly $350 to $580 every month compared to a low-down conventional loan. And with full entitlement there is no VA loan limit, so a qualified California veteran can purchase well above the conforming limit with no down payment, a rare advantage in high-cost coastal markets. Combined with typically the lowest interest rates available to any borrower, the VA loan is usually the single strongest financing option for those who have served.
Zero Down Payment
In California's expensive markets, saving 20% for a down payment can take decades. VA loans eliminate this barrier entirely.
No Mortgage Insurance
VA loans never require PMI, regardless of down payment. This saves California veterans hundreds per month.
Can I use a VA loan near California military bases?
Yes, and California has the largest military footprint in the nation, which anchors several of its strongest VA markets. In Southern California, Camp Pendleton (Marines) in San Diego County, Naval Base San Diego and Naval Base Coronado (Navy), and MCAS Miramar (Marines) make San Diego one of the best VA markets in the country. In the Central Valley and inland, Edwards Air Force Base (Kern County), Fort Irwin (San Bernardino), Naval Air Station Lemoore (Kings County), and Beale Air Force Base (Yuba County) serve large military populations. In Northern California, Travis Air Force Base (Solano County) is a major hub. For veterans buying near any of these, I handle active-duty purchases, PCS-timed remote closings, and jumbo-VA for higher-priced markets like Coronado. See the San Diego market for the Camp Pendleton and Coronado area.
What California-specific veteran benefits can I use?
Beyond the federal VA loan, California adds two valuable programs. The CalVet Home Loan Program is a state-run home loan, where CalVet holds the loan directly and can offer competitive, sometimes below-market rates under certain conditions. It requires California residency and can be combined with your federal VA entitlement. Second, California's disabled-veteran property tax exemption is among the most generous in the country: qualifying veterans with a service-connected disability can exempt a significant portion of their home's assessed value, and those rated 100% can receive a full exemption, saving thousands of dollars per year in a high-property-value state. For a disabled California veteran, that annual tax savings materially lowers the true monthly cost of ownership, and I factor it into your planning.
CalVet Home Loan Program
State-funded home loan program with competitive rates. CalVet holds the loan directly and may offer rates below market in certain conditions.
- California residency required
- Can combine with federal VA entitlement
- Available for purchase or refinance
Disabled Veteran Property Tax Exemption
California disabled veterans may qualify for property tax exemptions up to $254,656 of assessed value, significant savings in high-value markets.
- 100% exemption for qualifying veterans
- Saves $2,500-$3,000+ annually
- Service-connected disability required
VA IRRRL Streamline Refinance
Already have a VA loan? The Interest Rate Reduction Refinance Loan (IRRRL) lets you lower your rate with minimal documentation and no appraisal.
Calculate VA IRRRL Savings →Do I qualify for a VA loan in California?
Eligibility is based on your service history, and most veterans, active-duty members, qualifying National Guard and Reserve members, and eligible surviving spouses can qualify. You will need a Certificate of Eligibility confirming your entitlement, which I can help you obtain quickly, often instantly. The VA sets no minimum credit score, though most lenders look for around 620, and I work with lenders across the range. The VA uses a residual income test, measuring what you have left after major monthly obligations, rather than relying only on a debt-to-income ratio. In California's high-cost markets, this residual income approach often lets veterans qualify for more than a strict ratio would allow, especially when BAH is counted as income for active-duty buyers.
Can I buy a multi-unit property in California with a VA loan?
Yes, and it is a smart strategy in California's expensive markets. VA loans allow the purchase of 1 to 4 unit properties as long as you occupy one unit as your primary residence. In high-cost California markets, the rental income from the other units can help you qualify for a higher-priced property while a tenant helps cover your mortgage. This "house hacking" approach is especially popular with younger service members and veterans building wealth in markets where a single-family home would otherwise be out of reach. I structure these deals so the projected rental income is counted correctly toward your qualification.
How does a VA loan compare to other California loans?
For most eligible California veterans, VA is the clear winner. Against conventional, VA wins on down payment (zero versus 3 to 20%) and mortgage insurance (none versus PMI) for buyers without a large down payment. Against FHA, VA wins on both down payment and the absence of mortgage insurance. The main reasons a California veteran might use another loan are for a property type VA does not allow (a pure investment property or second home), or occasionally for a condo that is warrantable conventionally but not VA-approved, which happens in California's condo-heavy urban markets. I check VA condo approval early. First-time-buyer veterans should also know about the Price Equalizer on conventional loans, though the VA's zero-down, no-PMI structure usually makes VA the better choice.
Calculate Your California VA Loan Payment
See your estimated payment with $0 down and no PMI. Compare VA rates to conventional financing.
California VA Loan FAQs
Is there a VA loan limit in California for 2026?
For veterans with full VA loan entitlement, there is no loan limit, you can buy any priced home with $0 down. If you have reduced entitlement (previous VA loan or foreclosure), county loan limits apply, ranging from $832,750 in standard areas to $1,249,125 in high-cost California counties.
What is the VA funding fee in California?
The VA funding fee for California VA loans is 2.15% for first-time use with zero down, or 1.25%-1.5% with 5%-10%+ down payment. The fee can be financed into the loan. Veterans with service-connected disabilities are exempt from the funding fee.
What are the CalVet home loan benefits?
CalVet offers California veterans additional benefits including the CalVet Home Loan Program with competitive rates, property tax exemptions for disabled veterans (up to $254,656 exemption), and the California Military Family Relief Fund for emergency assistance.
Can I use a VA loan to buy a multi-unit property in California?
Yes! VA loans allow purchase of 1-4 unit properties in California, as long as you occupy one unit as your primary residence. This is popular in expensive markets where rental income helps qualify for higher-priced properties.
Is San Diego a good place to use a VA loan?
One of the best in the country. San Diego is a major Navy and Marine Corps city, and VA offers zero down, no PMI, no loan limit with full entitlement, and counts BAH as income.
Can California disabled veterans reduce their property taxes?
Yes. California's disabled-veteran exemption can exempt a significant portion of assessed value, with a full exemption for those rated 100%, saving thousands per year in a high-value state.
Explore More California Loan Options
Thank You for Your Service
Emmett Clark | CA-DRE #01408122
Let me help you use the benefits you've earned. Check your VA loan eligibility today.
Estimate Your VA Loan Payment
Adjust the numbers below for an estimated monthly payment on a VA purchase loan, with $0 down, the VA funding fee built in, and no monthly mortgage insurance.
From the blog & learning center
VA Loan Guides & Articles
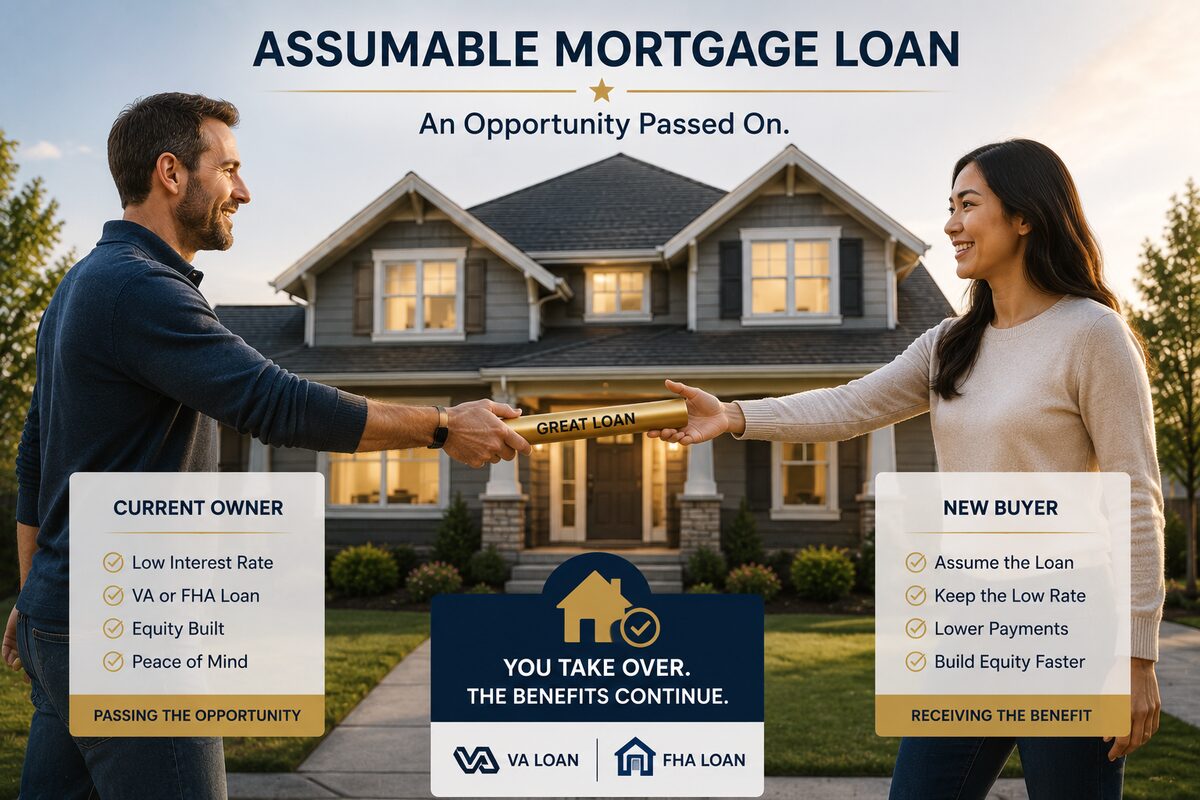
Assumable Mortgages: How to Take Over a VA or FHA Loan
An assumable mortgage lets a buyer take over a seller's VA, FHA, or USDA loan and its low rate. Learn the costs, the equity gap, and how to finance it.
Read more
Gift Funds: The Rules for Down Payment Gifts
A family member can give you money for your down payment, and on most loan types the entire down payment can be a gift. The key rules: it has to be a true gift with no repayment expected, it must come from an acceptable source, and it has to be documented with a gift letter and a clear paper trail.
Read moreSeller Concessions: How Much Can the Seller Pay?
A seller concession is when the seller agrees to pay part of your closing costs as a term of the sale. It's a legitimate, common way to reduce your cash to close, and depending on the loan type and your down payment, a seller can contribute anywhere from 2% to 9% of the purchase price toward your costs.
Read moreWhat Credit Score Do You Need for Each Loan Type?
The minimum credit score depends entirely on the loan program: FHA goes as low as 500-580, VA and USDA have no federal minimum (lenders typically want 580-640), conventional generally starts around 620, and jumbo loans want 700 or higher. Here's the breakdown by program.
Read more
How Can You Buy a House With No Money Down?
Two true zero-down loans exist: VA for veterans and military, and USDA for eligible rural and suburban homes. A few other paths get you close.
Read more
What does a VA renovation loan really involve?
A VA renovation loan lets an eligible veteran buy or refinance a home and finance non-structural repairs into the same VA loan with no down payment. The main hurdle is finding a lender who offers it.
Read more