Colorado Mortgage Broker
Your Rocky Mountain Home Financing Expert
A Colorado mortgage broker shops your loan across many wholesale lenders instead of a single bank's products, which usually means lower rates. As an independent broker licensed in Colorado (NMLS #233747), I compare 240+ wholesale lenders to find your best rate and help you access CHFA down payment assistance, including CHFA FirstStep and other programs.
Why do Colorado homebuyers choose mortgage brokers?
Colorado's housing market remains one of the hottest in the nation. With median prices in Denver exceeding $600K, even small rate differences translate to major savings. A 0.25% rate reduction on a $600K loan saves over $30,000 in interest over 30 years. Before you shop, it is worth getting your Colorado pre-approval started so you know your true budget.
Mortgage Broker
- Access to 240+ wholesale lenders
- Wholesale rates (typically 0.125-0.25% lower)
- Matches your scenario to best-fit lender
- Works for you, not the bank
- One application, multiple options
Direct Lender/Bank
- Only their own products available
- Retail rates with built-in margin
- May decline non-standard scenarios
- Loan officer works for the bank
- Must reapply at each lender
Colorado Housing Programs We Access
CHFA FirstStep
Up to 3% down payment assistance through Colorado Housing and Finance Authority. Available statewide for qualified first-time buyers with income limits.
FirstStep Plus
Up to 4% down payment/closing cost assistance with slightly higher interest rate. Great option for buyers who need maximum assistance.
Mountain Resort Areas
Aspen, Vail, and Breckenridge, we know which lenders specialize in high-cost mountain properties and vacation home financing.
Meet Your Colorado Mortgage Broker
I'm Emmett Clark, and I've spent over 20 years helping families navigate the mortgage process. With two Master's degrees and a broker's license, I bring both analytical expertise and practical experience to every transaction.
As an independent broker, I'm not employed by any single bank or lender. My job is to find you the best loan from my network of 240+ wholesale lenders, whether that's a major bank, credit union, or specialty lender that fits your unique situation.
Colorado's diverse markets, from Denver tech corridors to mountain resort communities to Colorado Springs military families, require customized solutions. I've helped thousands of borrowers find loans that conventional banks couldn't offer. For a broader look at programs and assistance across the state, see the full Colorado mortgage guide.
Learn More About Emmett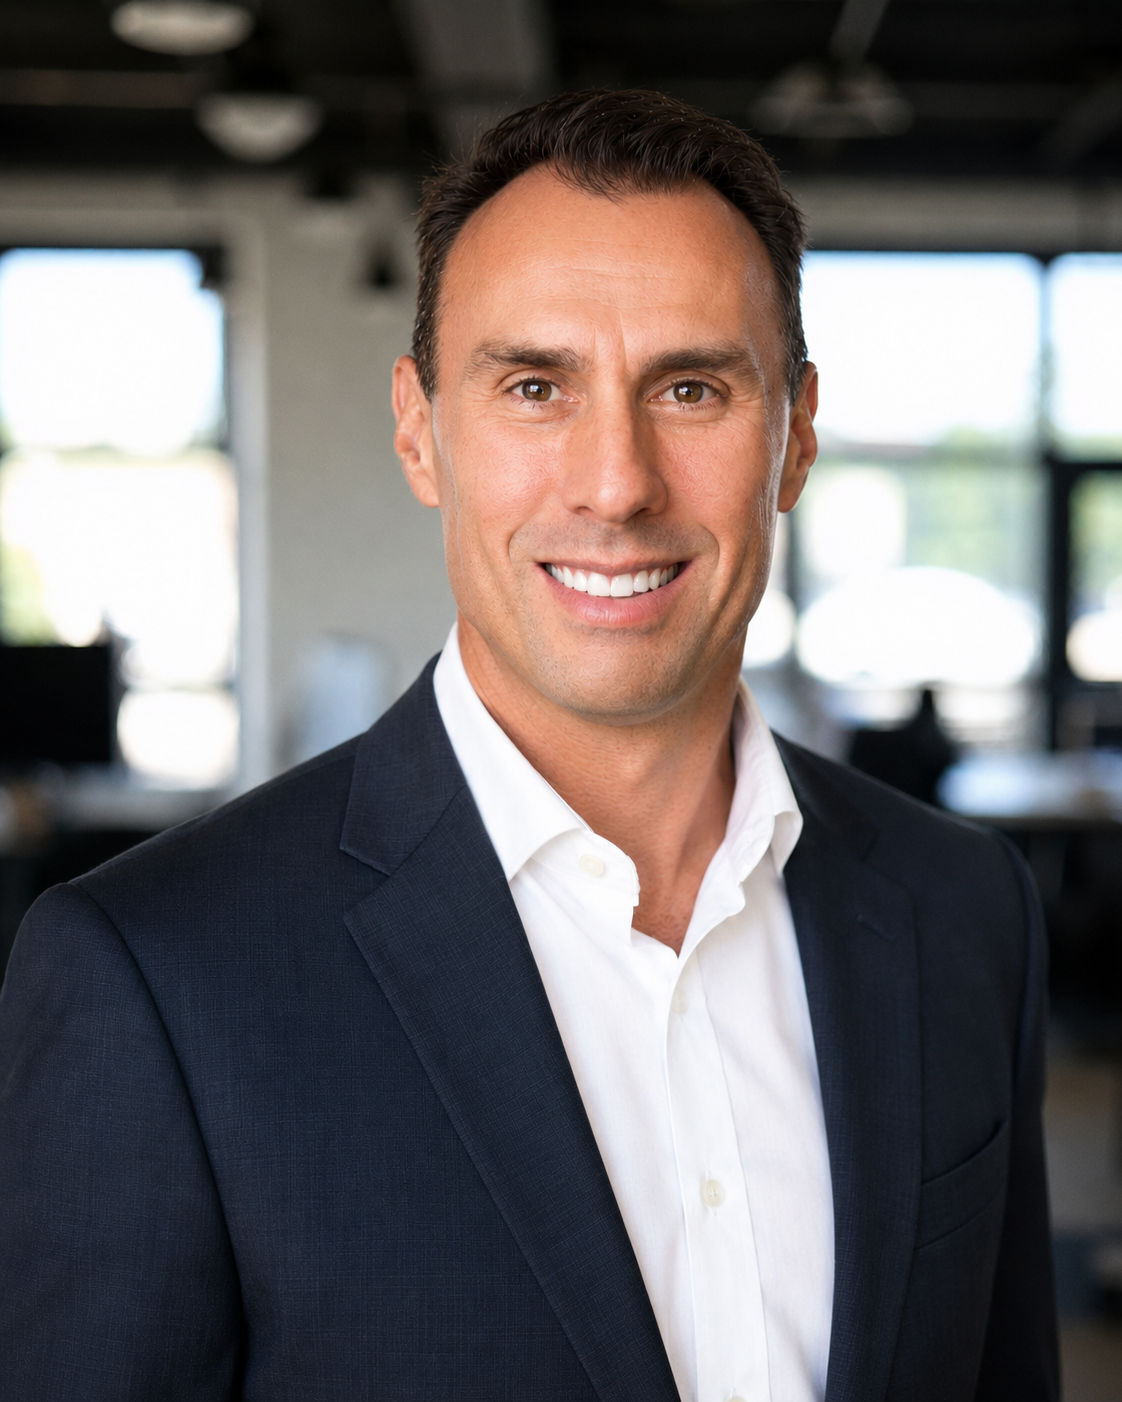
5-Star Google Reviews
$1,000 Best Price Guarantee
Close a loan with any lender for a lower combination of interest rate, fees, and monthly mortgage insurance? We'll send you a $1,000 check. That's how confident we are in our wholesale lender network.
Share Your Loan Estimate
Send us your competitor's LE to compare
We Try to Beat It
Rate, fees & mortgage insurance combined
Close & Get Paid
Show Final CD within 10 days, get $1,000
Which Colorado markets do you serve?
From the Front Range to the Western Slope, I help Colorado buyers in every major market. Each region has unique challenges, and I know which lenders serve each area best.
Denver
Denver County
Colorado Springs
El Paso County
Aurora
Arapahoe County
Fort Collins
Larimer County
Lakewood
Jefferson County
Boulder
Boulder County
Arvada
Jefferson County
+ All CO
Aspen, Vail, Pueblo & more
Colorado Loan Programs Available
FHA Loans
3.5% down
VA Loans
$0 down
Conventional
3-20% down
Jumbo Loans
Up to $5M
What Colorado Clients Say
"Denver's market moves fast. Emmett got me pre-approved and found a lender who could close in 21 days. Beat out 5 other offers on my dream home in Highlands!"
Michael T.
First-Time Buyer, Denver CO
"As a military family in Colorado Springs, VA loans are essential. Emmett found a lender with the lowest fees we'd seen. Saved us over $4,000 at closing."
Jennifer M.
VA Buyer, Colorado Springs CO
Get Your Mortgage Quote
Connect with Emmett directly. Quick response, personalized guidance for your Colorado home purchase.
Why Contact Emmett?
- ✓ Local Colorado market expertise
- ✓ Access to 240+ wholesale lenders
- ✓ Same-day pre-qualification available
- ✓ No obligation, free consultation
Colorado Mortgage Broker FAQs
What is the difference between a mortgage broker and a lender in Colorado?
A Colorado mortgage lender (like a bank or credit union) offers only their own loan products at their set rates. A mortgage broker is an independent professional who shops your loan across multiple wholesale lenders to find the best rate and terms. Brokers access wholesale pricing not available directly to consumers, often 0.125-0.25% lower than retail rates.
Can a mortgage broker help with CHFA programs in Colorado?
Yes! Colorado offers excellent state programs through CHFA including FirstStep down payment assistance (up to 3%), FirstStep Plus (up to 4%), and SectionEight Homeownership programs. A good Colorado mortgage broker knows which lenders are approved for these programs and can help you qualify.
Why should I use a mortgage broker instead of my bank in Colorado?
Mortgage brokers have access to wholesale rates from multiple lenders, often 0.125-0.25% lower than retail bank rates. In Colorado's high-cost housing markets like Denver, Boulder, and Aspen, this can save you tens of thousands over your loan term.
What is the $1,000 Best Price Guarantee?
If you close a loan with any lender for a lower combination of interest rate, fees, and monthly mortgage insurance, we'll send you a $1,000 check. Simply share your Loan Estimate so we can compare. If we can't beat it and you close with the competitor, show us the Final Closing Disclosure within 10 days and we'll pay you $1,000.
From the blog & learning center
Colorado Home Buying Guides
Condo Loan Denied Over the HOA? FHA Single Unit Approval May Save the Deal
If your condo loan was denied because of the HOA project itself, not your credit, FHA Single Unit Approval may still get you to closing. Here is how it works.
Read more
How to Buy a House After Divorce
Buying after divorce means untangling the old mortgage, documenting support income, and qualifying on your own. Here is how to prepare and what lenders look at.
Read more
FHA-Approved Condos in Hawaii: Why the List Is Short, and How to Find One
Only a small number of Hawaii condos are FHA-approved, so you must confirm a unit qualifies before you fall in love with it. Here is how FHA condo approval works in Hawaii.
Read more
Can You Buy a 5 to 8 Unit Property With an FHA Loan?
No. FHA financing caps at 4 units. A 5-unit-or-larger building is commercial and needs different financing. Here is why, and what to use instead.
Read more
Buying a House After Bankruptcy: Real Waiting Periods by Loan Type
FHA and VA require 2 years after Chapter 7, USDA 3, conventional 4. Chapter 13 can qualify after 12 months of payments, and one program works during bankruptcy.
Read more
Buying After Foreclosure or Short Sale: The Real Timelines
After foreclosure, VA requires 2 years, FHA and USDA 3, conventional 7. Short sales are shorter, and some paths skip the waiting period entirely.
Read more